CLARITY Act Hits a Senate Wall: What the Failed 49–50 Vote Means for U.S. Crypto Regulation
The most ambitious attempt to establish a comprehensive regulatory framework for digital assets in the United States has encountered a major obstacle. On September 15, 2026, the U.S. Senate rejected a motion to invoke cloture on proceeding to the CLARITY Act (H.R. 3633) by a vote of 49–50, falling short of the 60 votes required. The result does not represent a final rejection of the legislation, but it means that the Senate did not proceed to consideration of the bill at that stage and leaves the future of U.S. crypto market structure regulation uncertain.
A Procedural Defeat, Not a Final Vote
The Senate vote concerned cloture on the motion to proceed to H.R. 3633, rather than final passage of the CLARITY Act itself. According to the official Senate record, 49 senators voted in favor, 50 voted against, and one did not vote. The motion therefore fell 11 votes short of the 60-vote threshold required for cloture. Republicans Susan Collins, Josh Hawley, Jerry Moran and Thom Tillis joined Democrats and independents present in voting against advancing the measure, while Senator Chris Coons did not vote.
This is an important distinction because the CLARITY Act had already cleared the House of Representatives in July 2025 by a bipartisan vote of 294–134, including support from 78 Democrats. The failed Senate vote means lawmakers did not move to the next stage of floor consideration, where amendments, debate and eventually a vote on final passage could have followed. In practical terms, the legislation has been stalled rather than formally defeated.
What the CLARITY Act Was Designed to Change
At the centre of the legislation is the long-standing question of how regulatory responsibility for digital assets should be divided between the Securities and Exchange Commission (SEC) and the Commodity Futures Trading Commission (CFTC). The proposal would give the CFTC broader authority over digital commodity spot markets and registered exchanges, brokers and dealers, while preserving the SEC’s role in securities and investment-contract transactions. The legislation would also establish requirements for relevant registered intermediaries covering customer asset segregation, disclosures, capital, risk management and custody.
The version prepared for the September vote included substantial additional provisions beyond the original House text. It addressed the treatment of certain DeFi protocols under the Bank Secrecy Act, clarified rules for credit unions and introduced additional provisions related to payment stablecoins. Its Republican sponsors said the final draft incorporated 126 substantive changes requested by Democrats, including stronger ethics provisions, a role for state attorneys general in enforcing restrictions on government officials and new Treasury authority intended to respond to potential deposit outflows linked to stablecoins.
Why the Senate Failed to Reach the Required Support
One of the central unresolved disputes concerned ethics rules for elected officials with financial interests in digital assets. Democratic senators argued that the final proposal did not go far enough in preventing conflicts of interest involving federal officials, with particular attention focused on President Donald Trump’s crypto-related business interests. The final draft expanded enforcement by allowing state attorneys general to take action under certain circumstances, but Democratic negotiators continued to seek stronger requirements, including additional divestment provisions.
The disagreement was not limited to ethics. Banks and some lawmakers had also raised concerns that rewards linked to payment stablecoins could encourage deposits to move away from traditional banks and potentially affect their lending capacity. The final proposal therefore included additional Treasury powers aimed at limiting deposit flight. Despite these changes and months of negotiations, no Democrat voted in favor of the motion to invoke cloture on proceeding to the bill, while several Republicans also voted against it.
The Bill Is Stalled, but the Door Is Not Completely Closed
One procedural detail keeps the CLARITY Act technically alive. Senator Thom Tillis changed his vote to “no” and subsequently entered a motion to reconsider the vote, leaving open a procedural route for the Senate to revisit the matter. This means another attempt to advance the legislation remains possible. However, as of September 16, no new CLARITY Act vote has been scheduled, and Congress is approaching the November midterm elections, which may affect the remaining legislative timetable.
Until Congress reaches a new agreement, attention is likely to remain on the SEC and CFTC and the rules they can develop within their existing statutory authority. Senate Banking Committee Chairman Tim Scott and the House committee chairs behind the legislation identified agency rulemaking and guidance as one possible avenue while Congress continues working on statutory legislation. The failed vote therefore does not end digital asset regulation in the United States, but leaves the effort to establish a comprehensive federal legislative framework unresolved.
Warning: The content of this article is intended exclusively for informational purposes and does not constitute investment advice or a recommendation to purchase a specific asset. Investments in crypto-assets involve a high level of risk. The value of crypto-assets may fall as well as rise, and you may lose the entire amount invested. Crypto-assets are not protected by deposit guarantee schemes. Past returns are not a guarantee of future results.
Author
Tomáš Bára
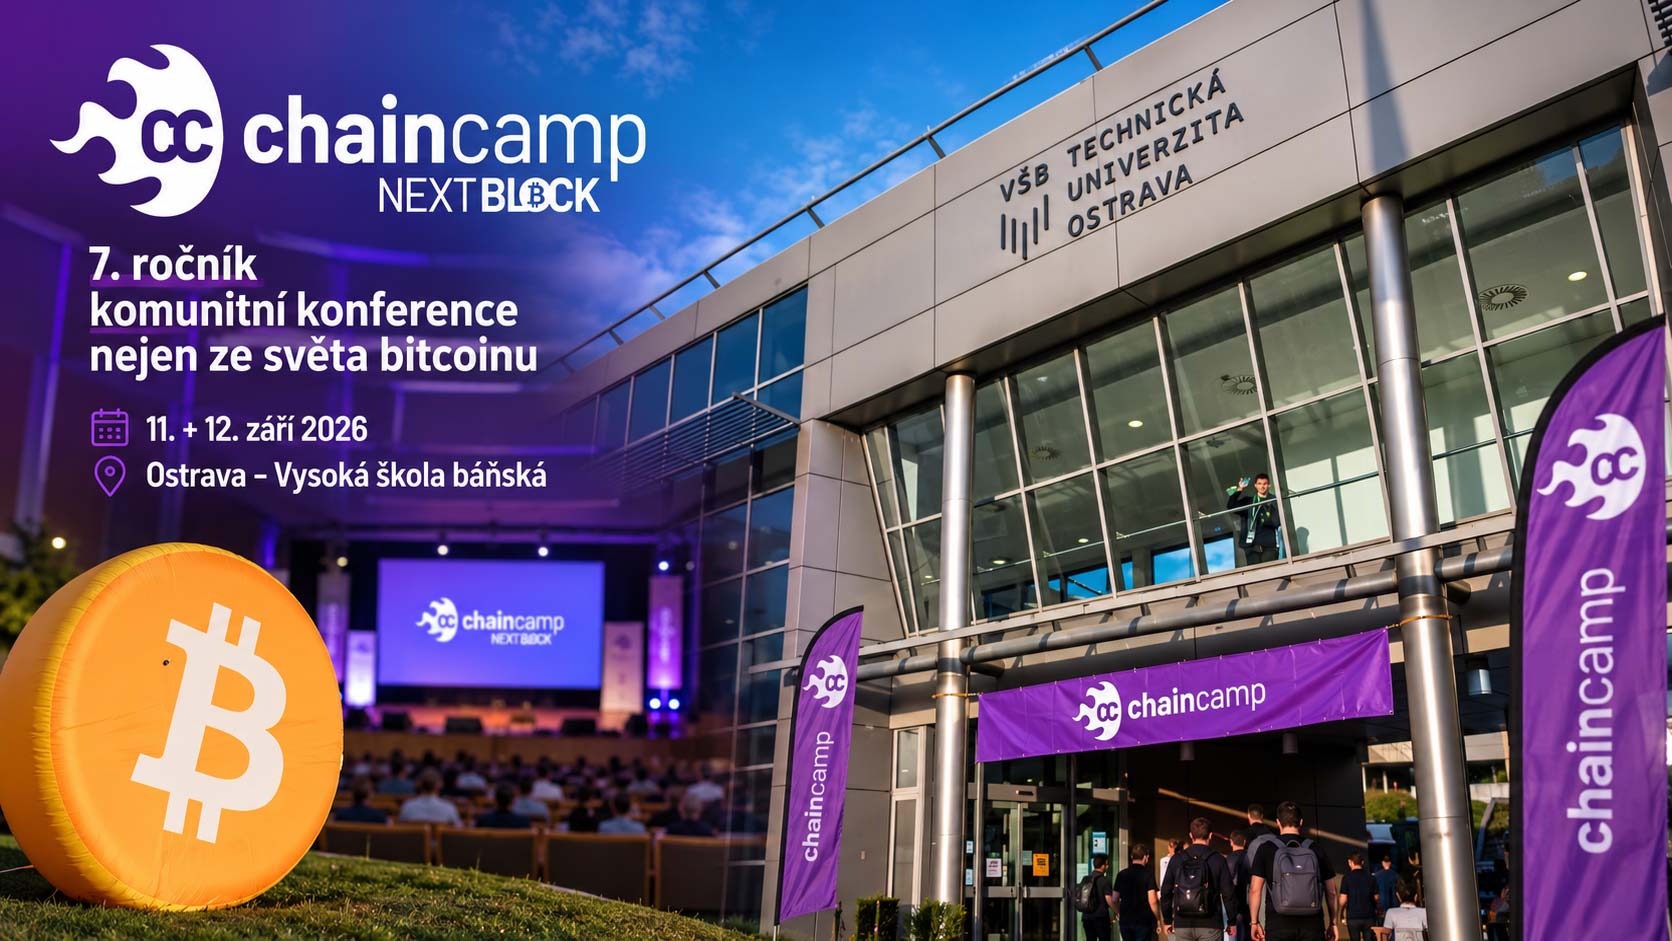
ChainCamp 2026 brought together Bitcoin, personal freedom and the Czech and Slovak community
The seventh edition of the ChainCamp conference brought the Czech and Slovak Bitcoin community to Ostrava on September 11 and 12. Alongside Bitcoin, this year's topics also included asset protection, privacy and a personal Plan B. Brand manager Tomáš Bára attended the event on behalf of crypto4me and shares his impressions.
Change in the Monetary Regime: A Second Inflation Wave and 5% Bond Yields
The shift from expected monetary policy easing to the threat of further tightening is changing conditions for the digital asset market. The combination of more expensive oil, unfavorable inflation data and rising U.S. bond yields is creating an environment for Bitcoin that it has not faced since the end of 2023.